Welcome David Ditch to the Debt Dispatch! We are pleased to announce a new regular contributor: David Ditch will be joining the Cato Institute as a Policy Analyst for Budget and Entitlement Policy later this week. David has more than a decade of experience in fiscal policy issues, with a particular focus on federal spending. He previously worked at the Senate Budget Committee, the Heritage Foundation, and the Economic Policy Innovation Center. David’s areas of expertise include appropriations, transportation, agriculture, federalism, grantmaking, and policy options for deficit reduction. Originally from the Rochester, N.Y. area, David has a BA in Economics and Political Science from the University of Rochester and a MA in Political Management from George Washington University. David currently lives in Arlington, VA. You may have enjoyed his earlier guest posts:
CBO: New Highway Bill Has More Spending, Taxes, and Deficits
Trump Administration’s Proposed Changes to Federal Grants Highlight Problems of Big Government

Here are this week’s reading links and fiscal facts:
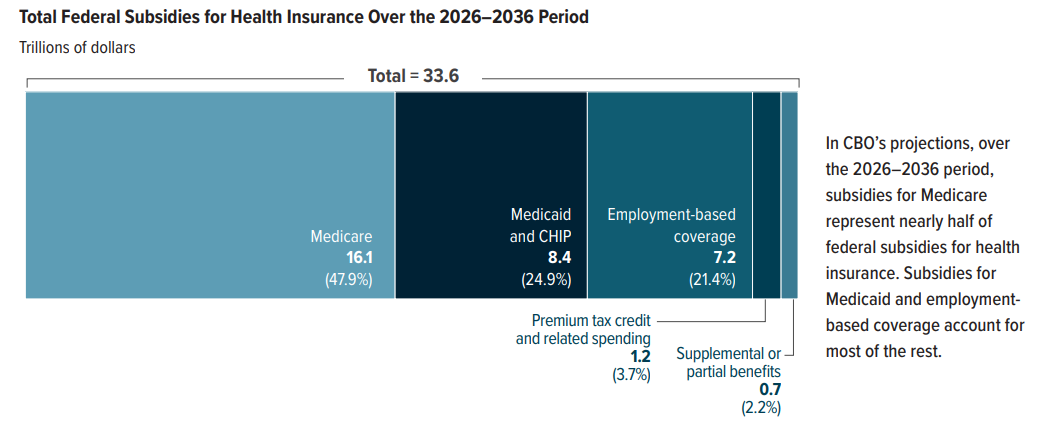
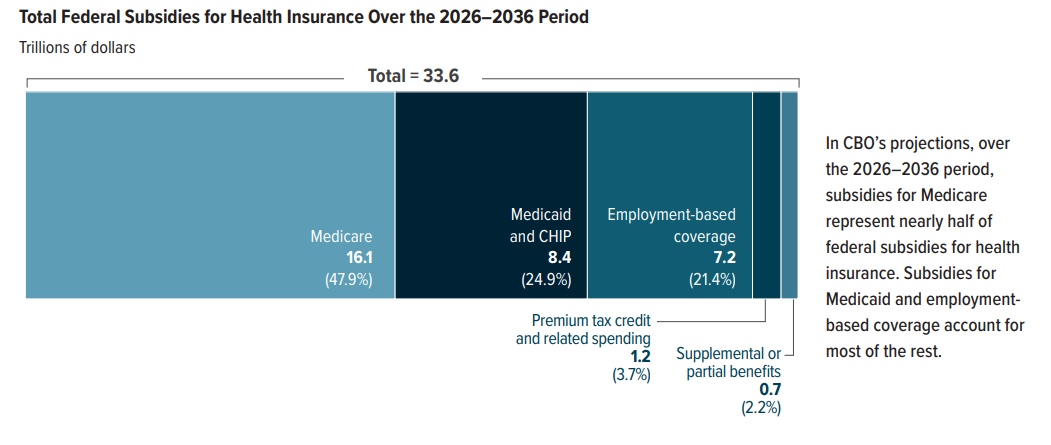
The federal debt is largely a health care problem. In a new report, the Congressional Budget Office and Joint Committee on Taxation find that “In 2026, federal subsidies for health insurance, net of related payments to the government, are projected to equal $2.4 trillion, or 7.4 percent of gross domestic product (GDP). In CBO and JCT’s projections, those subsidies grow by 65 percent, reaching $3.9 trillion, or 8.4 percent of GDP, in 2036. Subsidies for Medicare contribute most to that overall growth, increasing by $900 billion. Over the entire 2026–2036 period, federal subsidies for health insurance total $33.6 trillion.” Cato’s Michael Cannon emphasizes, “The long-term federal debt problem is a health care problem. […] Only two categories of federal outlays will grow faster than gross domestic product (GDP): health care subsidies and interest payments on the debt. The former is, therefore, the primary driver of the latter.”
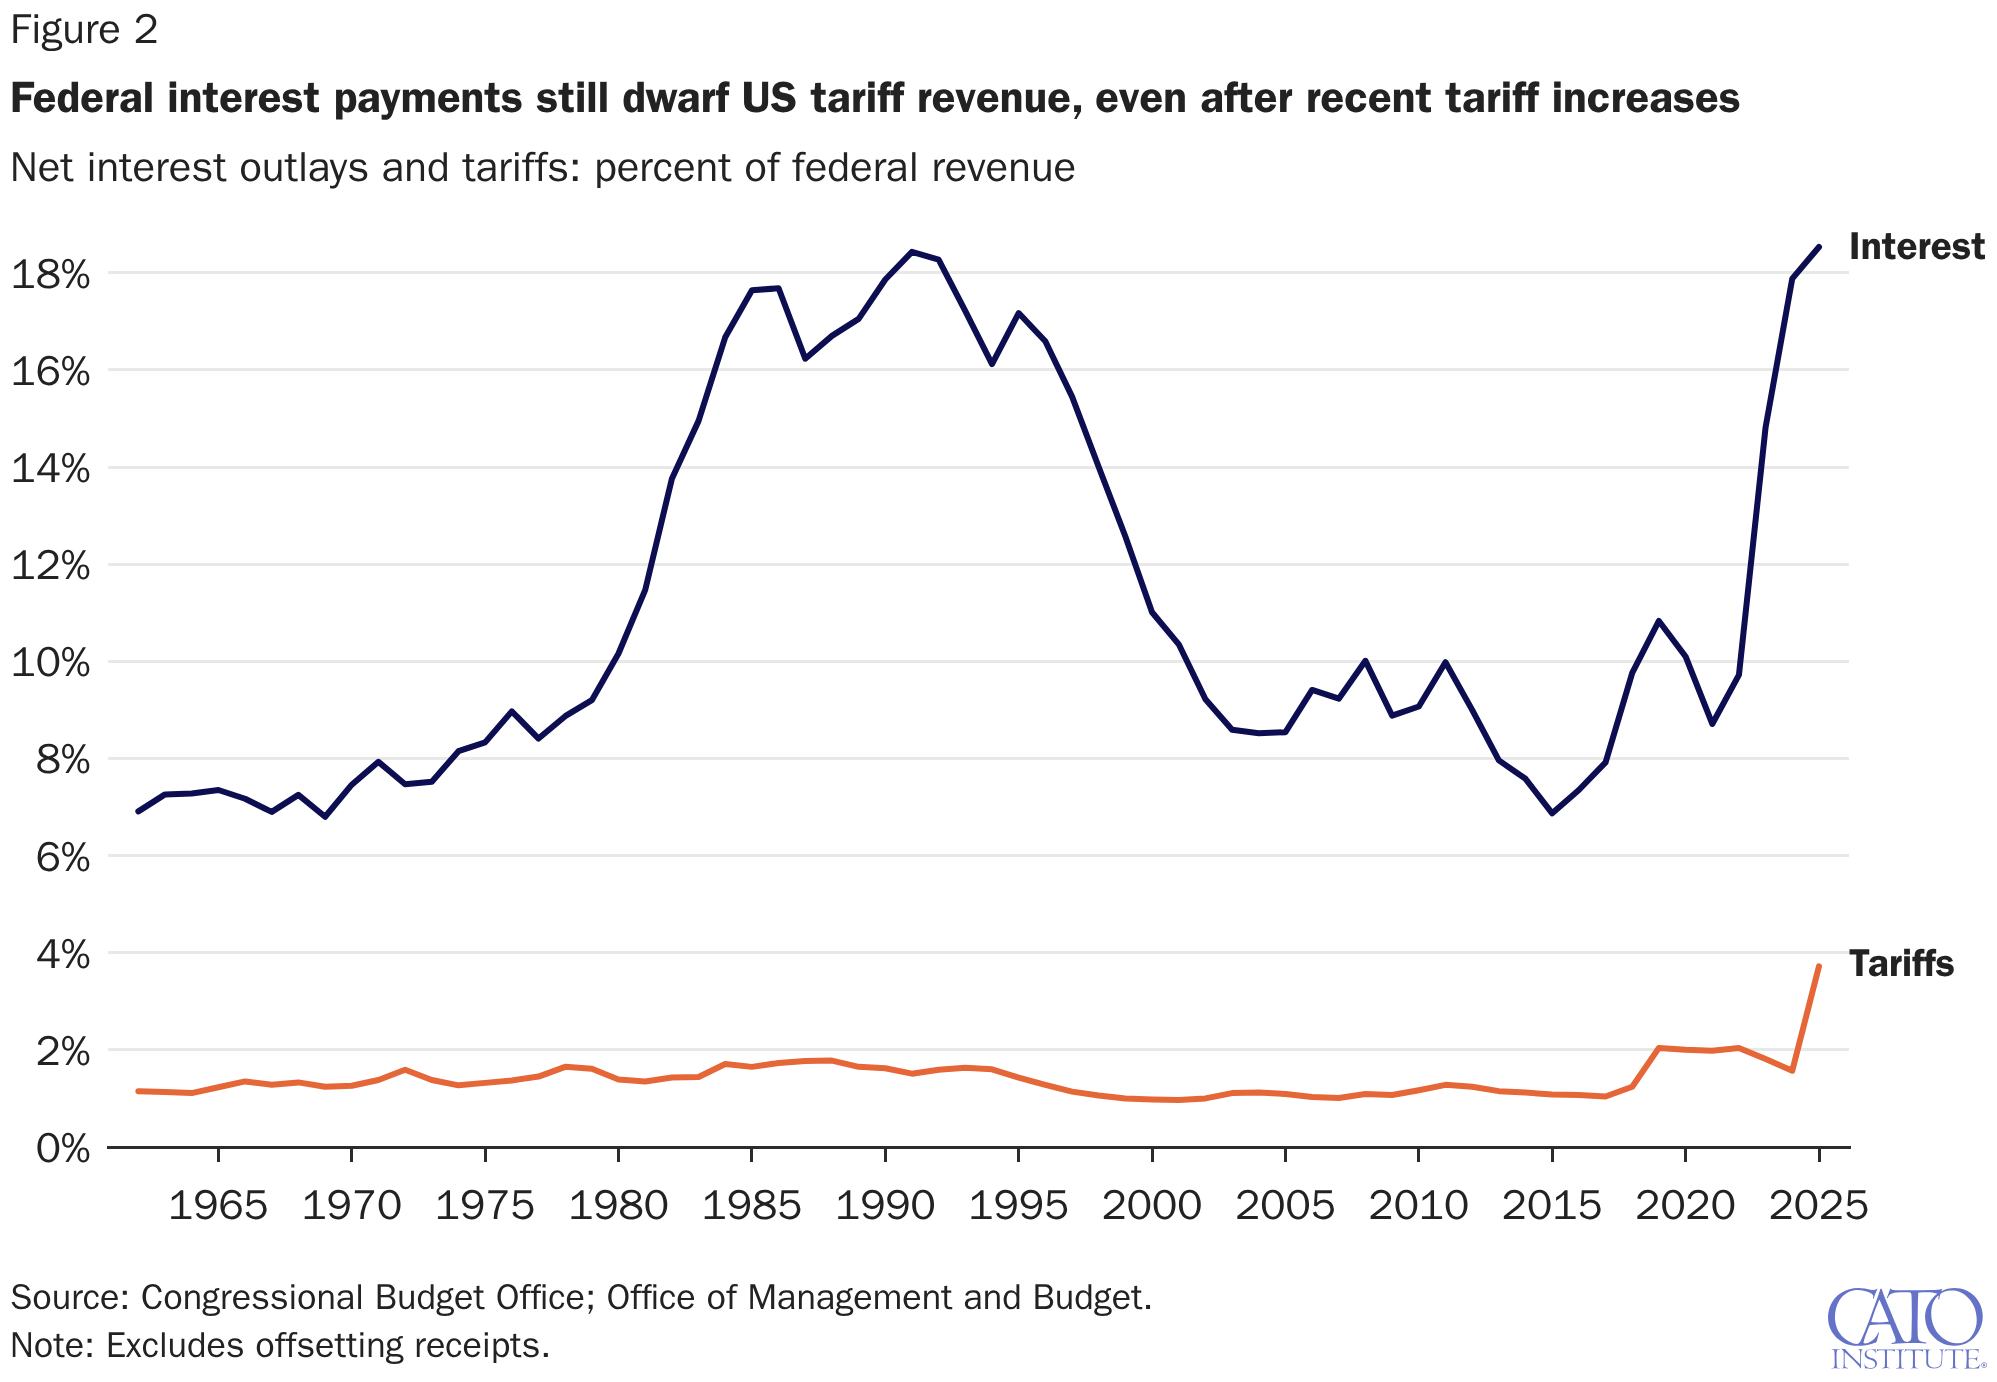
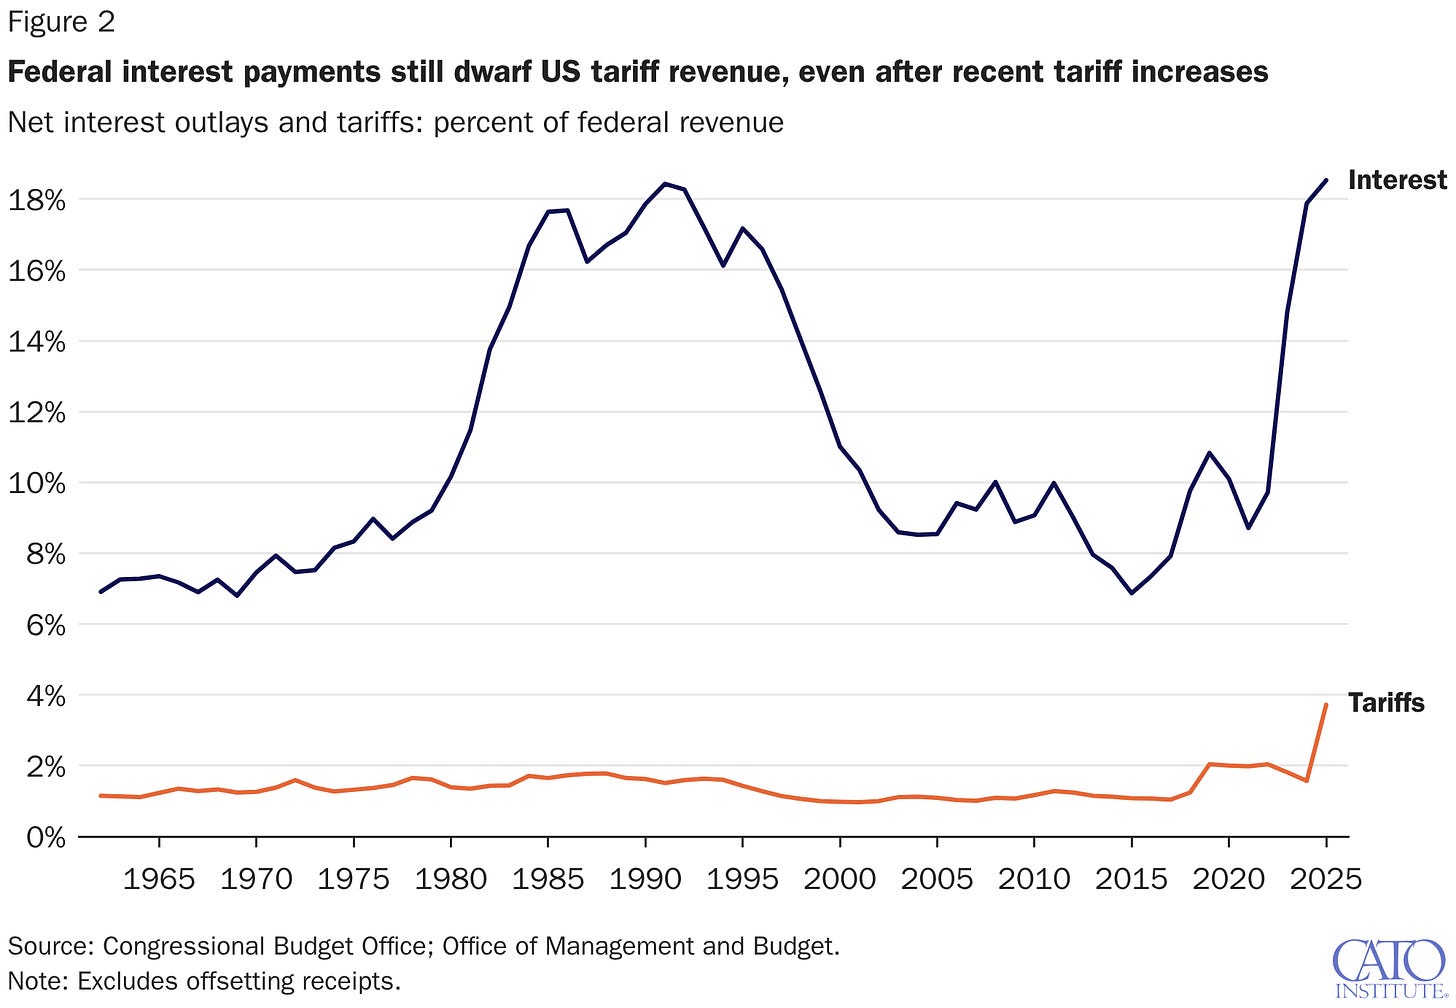
The bond market fears deficits, not the loss of tariff revenue. Responding to a New York Times essay claiming tariff revenue has grown too important for a future administration to unwind, Cato’s Kyle Handley argues: “Bond investors are not attached to customs duties as a line item revenue source. They care about the government’s overall fiscal position.” He continues, “tariff revenue is a side hustle. And the Trump administration has already promised to dole out the funds through schemes like tariff dividend rebates, farm subsidies, and pay-fors on tax cuts or other spending.” Furthermore, “tariff revenue is simply not large enough to transform the government’s fiscal trajectory.” Take net interest for example: it “reached $970 billion in fiscal year 2025, absorbing 18.5 percent of federal receipts. Customs duties accounted for only 3.7 percent of receipts—and that was before refunds (see Figure 2).” Handley concludes, “The real bond-market concern is a large and growing interest bill, persistent budget deficits, and a political system unwilling to bring spending and revenue into alignment.”
Medicare’s spending growth is driven by more volume and utilization. A Congressional Research Service report finds that Medicare spending “grew at an average annual rate of 7.3%” from 1985 through 2025, and the trustees project health care expenditures will keep rising “faster than gross domestic product (GDP) in most future years.” Citing CBO, the report attributes Medicare’s projected 2026–2036 spending growth to “23% from higher enrollment, 31% from inflation, and 47% from the growth of inflation-adjusted spending per beneficiary. In other words, the largest single driver of Medicare spending growth during the next decade is expected to be higher volume and intensity of health care services.” Boccia and Thakur explain: “as the economy grows, Medicare spending tends to grow at least as fast—and often faster—because the program automatically pays the bill for more and more healthcare consumption by seniors, even as prices rise.”
The Fed has little control over market interest rates. Cato’s Jai Kedia documents that the Fed has held its rate target steady since December, yet “nearly every rate Americans actually borrow at has climbed over the same stretch.” Kedia continues, “The Fed did nothing, and the cost of credit went up anyway. […] Markets spent these months repricing macroeconomic events such as sticky core inflation, a volatile energy market driven by the conflict in the Middle East, and global trade disrupted by tariffs, among others. None of that required a policy change to show up in borrowing costs because markets, not the FOMC, set prices.” He concludes, “Accurately priced borrowing rates will come from credible disinflation and disciplined budgets and from a Fed content to follow the economy rather than pretend it leads it.”
Nearly half of US farm income comes from taxpayers. Former Reagan OMB director David Stockman notes that “in the most recently completed full year (FY 2025) farmer incomes in the US totaled $97.8 billion, but fully 42.7% or $41.8 billion of that amount came from taxpayers, not the marketplace. Nor is this some kind of one-year aberration. If we look at the most recent decade as a whole, total farm income posted at nearly $708 billion, but, as indicated, fully $322 billion or 45% of this came compliments of US taxpayers.” Cato’s Chris Edwards explains why so little of that income is market-earned: “Farmers are businesspeople, but the government shields them from just about every type of weather and market risk. Furthermore, just about every part of the agricultural industry is subsidized, including insurance, loans, marketing, research, export sales, and land improvements.”